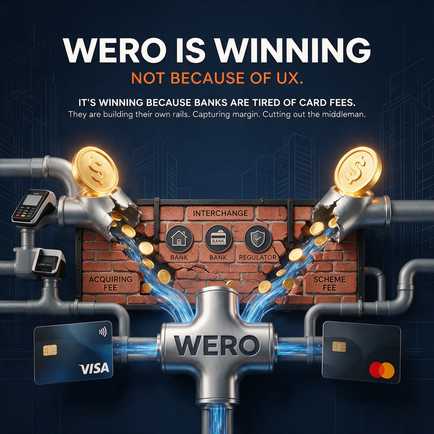

As Frederic Yves Michel NOEL highlights, Wero is not winning because consumers asked for another payment app. It is winning because European banks have spent two decades watching interchange revenue flow to Visa and Mastercard, and they are finally building rails they control.
The UX is fine. The rollout is decent. But the strategic driver is margin recapture. Every Wero transaction that bypasses card rails keeps acquiring fees, scheme fees, and interchange inside the banking system. That is not a consumer preference story. That is a commercial settlement story dressed up as innovation.
For PSPs, the risk is treating Wero as just another payment method to integrate. It is not. It is the first visible sign that banks are willing to compete with their own payment infrastructure at the point of sale and in peer-to-peer flows. PSPs that build Wero as a checkbox integration will miss the deeper shift: banks are reclaiming the merchant relationship, the data, and the economics.
My view: the next 24 months will separate PSPs that understand bank-owned rails as a strategic threat from those that still think scheme rails are neutral infrastructure.
For PSPs already mapping Wero into their payment stack, are you treating it as a local method or as a signal of where acquiring margins are heading?
#Wero #EPI #PSP #Acquiring #PaymentRails #SEPA #Interchange
Comments are closed